
Solicitors Specialising In the Creation And Administration Of Family Trust Funds 
Many grandparents want to help give their grandchildren the best possible start in life. You may wish to help with school fees, university costs, a first home, or simply pass on some of your wealth in a controlled and tax-efficient way. Creating trust funds for grandchildren can often be an effective way of doing this.
The right trust can allow money or other assets to be managed responsibly until your grandchildren are old enough or until certain circumstances arise. It can also help protect family wealth, reduce the risk of money being spent unwisely and, in some cases, assist with inheritance tax planning.
There is no single type of trust that suits every family. The most appropriate arrangement will depend on your financial circumstances, your wider estate planning objectives and the ages and needs of your grandchildren.
At Bonallack & Bishop, our private client solicitors regularly advise grandparents and families on creating trusts that protect family wealth for future generations,
If you are considering setting up a trust fund for your grandchildren, obtaining specialist legal advice at the outset can help ensure that the trust achieves exactly what you want it to do.
For FREE initial phone advice and a no obligation quotation from one of our specialist Trusts lawyers, call FREEPHONE 0800 1404544 or one of our local office numbers [see below]
Specialist Trust Advice From Elizabeth Webbe TEP
Our highly specialist trust solicitor, Elizabeth Webbe, is a Full Member of STEP (TEP). STEP (the Society of Trust and Estate Practitioners) is the internationally recognised professional body for specialists who advise families on trusts, estates and wealth planning.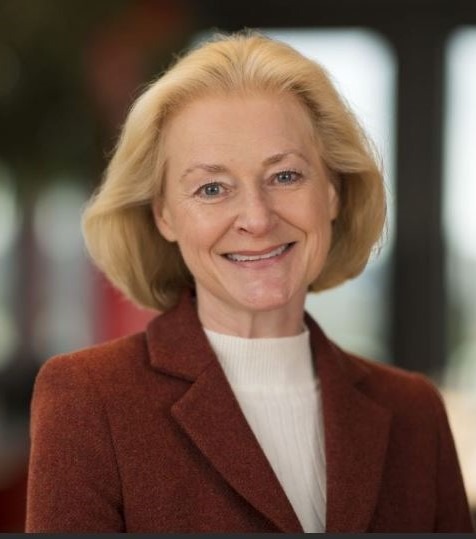
Full STEP membership represents the highest level of professional membership and is recognised throughout the legal and financial professions as a mark of substantial expertise in trust and estate planning.
Elizabeth regularly advises clients on:
- creating trusts;
- discretionary trusts;
- bare trusts;
- trust funds for grandchildren;
- inheritance tax planning;
- trustee appointments;
- trust administration;
- protecting family wealth across generations.
If you are considering establishing a trust fund for your grandchildren, specialist advice at an early stage can help ensure your wishes are carried out effectively while avoiding unnecessary legal and tax complications. 
________________________________________
What Are Trust Funds For Grandchildren?
A trust is a legal arrangement under which assets are held by one or more trustees for the benefit of other people, known as beneficiaries.
When grandparents create a trust for grandchildren, the trustees become responsible for managing the assets in accordance with the terms of the trust.
The assets placed into the trust might include:
- Cash
- Investments
- Shares
- Property
- Business interests
- Life insurance proceeds
The trustees have legal duties to manage those assets responsibly and in the best interests of the beneficiaries. Those duties arise under both the terms of the trust itself and legislation including the Trustee Act 2000, which sets out many of the responsibilities of trustees.
Unlike simply giving money directly to a grandchild, a trust allows you to decide:
- who should benefit;
- when they should benefit;
- how much they should receive;
- who will make decisions in the future; and
- what should happen if circumstances change.
For many families, this additional control is one of the main reasons for using a trust.
________________________________________
Why Do Grandparents Set Up Trust Funds?
Every family is different, but common reasons include protecting assets and helping future generations without giving away complete control immediately.
Many grandparents use trusts to:
- help pay private school fees;
- contribute towards university costs;
- assist with buying a first home;
- build long-term investments;
- protect gifts until grandchildren are older;
- provide for grandchildren with disabilities or vulnerabilities;
- preserve family wealth across generations;
- reduce the risk of money being lost following relationship breakdowns;
- assist with inheritance tax planning.
A trust can also help where grandparents want to treat grandchildren fairly while recognising that their individual needs may change over time.
________________________________________
Can Grandparents Simply Give Money Directly?
In short, yes and many grandparents simply transfer money directly to their grandchildren. For relatively modest gifts, this may be entirely appropriate.
However, once a gift has been made outright, the money generally belongs to the recipient immediately.
If the grandchild is under 18, the money will usually need to be managed by an adult until they become legally entitled to it.
Once the grandchild reaches adulthood, they will normally have complete freedom to spend the money however they wish.
For some families, that is perfectly acceptable.
For others, it may not reflect what the grandparents intended.
A trust provides a way of retaining an appropriate degree of protection while still benefiting future generations.
________________________________________
Protecting Gifts Until Adulthood
One of the biggest concerns grandparents express is that a substantial gift may be received before a grandchild is mature enough to manage it wisely.
Children and young adults develop at very different rates.
Some may be financially responsible at 18.
Others may benefit from receiving assistance later in life, perhaps after completing education, establishing a career or buying their first home.
A trust allows grandparents to decide how and when assets should be released.
Depending upon the type of trust chosen, trustees may:
- make payments gradually;
- pay educational expenses directly;
- release capital at specified ages;
- delay access until beneficiaries demonstrate financial maturity;
- retain funds for future generations if circumstances change.
This flexibility is often one of the greatest advantages of using a trust.
________________________________________
How To Set Up Trust Funds For Grandchildren In The UK
Although every family’s circumstances differ, establishing a trust usually follows a similar process.
Step 1 – Decide what you want the trust to achieve
Before choosing a trust, consider your objectives.
For example:
- Do you want to pay school fees?
- Are you helping with university costs?
- Should the money remain invested for many years?
- Do you want grandchildren to inherit equally?
- Should trustees have flexibility?
- Are inheritance tax savings an important consideration?
Being clear about your objectives helps identify the most suitable type of trust.
Step 2 – Choose the appropriate type of trust
There are several different trust structures available.
The most commonly used for grandchildren include:
- Bare Trusts
- Discretionary Trusts
- 18–25 Trusts
- Interest in Possession Trusts (in some circumstances)
Each has different legal and tax consequences.
The most appropriate choice depends on your family’s objectives rather than simply choosing the most familiar type of trust.
Step 3 – Appoint trustees
Choosing trustees is one of the most important decisions.
Trustees will be responsible for managing the trust, investing assets where appropriate and making decisions in accordance with the trust deed.
Many people appoint:
- adult children;
- other trusted relatives;
- close family friends;
- professional trustees; or
- a combination of family members and professionals.
Professional advice can be particularly valuable where significant assets are involved or where trustees are expected to exercise ongoing discretion.
Step 4 – Prepare the trust documentation
A trust should always be created using carefully drafted legal documentation.
The trust deed sets out:
- who the beneficiaries are;
- who the trustees are;
- the trustees’ powers;
- when distributions can be made;
- investment powers;
- administrative provisions;
- what happens if trustees retire or die.
Poorly drafted trust documentation can create uncertainty, tax problems or disputes many years later.
According to the trust solicitors at Bonallack & Bishop, investing in properly prepared trust documentation at the outset is usually far less expensive than resolving problems after the trust has been established.
Step 5 – Transfer assets into the trust
Once the trust has been established, the chosen assets are transferred into it.
Depending upon the assets involved, this may require:
- bank transfers;
- stock transfer forms;
- Land Registry documentation;
- valuation advice;
- tax reporting.
The transfer itself may have tax consequences, making specialist advice particularly important.
________________________________________
Bare Trusts For Grandchildren
A Bare Trust is one of the simplest forms of trust.
The trustees hold assets for a named beneficiary.
Although trustees manage the assets while the beneficiary is a child, the beneficiary has an absolute entitlement to the trust property.
In England and Wales, the beneficiary will usually become entitled to take control of the trust assets once they reach the age of 18, although there are ways to extend the life of a Bare Trust with advance planning.
Bare Trusts are commonly used where grandparents simply want investments to be managed until adulthood without giving trustees ongoing discretion.
-
Advantages Of A Bare Trust
- Simple structure.
- Relatively straightforward administration.
- Clear ownership.
- Often suitable for modest gifts.
- Useful for long-term investment.
-
Possible Disadvantages
- The beneficiary generally becomes absolutely entitled at 18.
- Trustees have limited flexibility once established.
- Assets cannot usually be redirected if family circumstances change.
For families seeking greater flexibility, a discretionary trust may sometimes be more appropriate.
________________________________________
Discretionary Trusts For Grandchildren
A Discretionary Trust gives trustees considerably greater flexibility. Rather than each beneficiary having a fixed entitlement, the trustees decide when and how assets should be distributed within the powers given by the trust deed.
This can be particularly useful where:
- grandchildren are of different ages;
- future needs are uncertain;
- family circumstances may change;
- one grandchild may require greater financial support than another;
- beneficiaries are not yet financially mature.
The trustees must exercise their discretion properly and in accordance with the terms of the trust. They cannot simply act according to personal preference.
A discretionary trust can therefore provide a high degree of protection while allowing trustees to respond to changing family circumstances over many years.
18–25 Trusts For Grandchildren
An 18–25 Trust is a special type of trust that may be appropriate in certain circumstances. It allows assets to be held for a young beneficiary after they reach the age of 18, with the capital becoming available no later than age 25.
The rules governing these trusts are contained principally within the Inheritance Tax Act 1984.
Unlike a discretionary trust, an 18–25 Trust is only available in particular situations and cannot simply be used whenever someone wishes. Specialist legal advice is important to determine whether this type of trust is available and appropriate.
-
Advantages Of An 18–25 Trust
Depending on the circumstances, an 18–25 Trust may:
- delay access to significant assets until greater maturity;
- provide trustees with greater control during early adulthood;
- offer tax advantages in some situations;
- allow funds to be used for education and maintenance before capital is distributed.
-
Possible Disadvantages
These kind of legal structures may not be suitable because:
- strict legal rules apply;
- it is not available in every situation;
- beneficiaries must normally become fully entitled by age 25;
- tax treatment can be more complex than with simpler trust arrangements.
Many grandparents ask specifically about 18–25 Trusts after reading about them online. However, in practice, a discretionary or bare trust is often more suitable, depending upon the family’s objectives.
________________________________________
Trust Funds for Grandchildren – Paying School Fees
Many grandparents wish to help with private education. Trust funds for grandchildren can provide an organised way of meeting educational costs while preserving capital for future needs.
Depending upon the terms of the trust, trustees may pay:
- school fees;
- boarding fees;
- educational equipment;
- specialist tuition;
- extracurricular activities;
- educational trips.
Rather than giving money directly to a child, trustees may pay educational providers directly where appropriate. This can provide reassurance that the money is being used for its intended purpose.
________________________________________
Helping With University Costs
University can represent one of the largest financial commitments faced by young adults. Grandparents often wish to help with:
- tuition fees;
- accommodation costs;
- living expenses;
- books and equipment;
- postgraduate study.
A trust may allow trustees to release money gradually throughout university rather than making one large payment.
This can encourage sensible financial management while ensuring support remains available throughout the course.
________________________________________
Using A Trust To Help Buy A First Home
Many grandparents hope to help grandchildren onto the property ladder.
Property prices continue to make this increasingly difficult for many first-time buyers.
Trust funds for grandchildren may provide cash towards:
- a deposit;
- legal costs;
- Stamp Duty Land Tax (where applicable);
- associated moving costs.
Some grandparents also wish trustees to consider whether a beneficiary is financially ready before substantial capital is released. A discretionary trust will provide that flexibility.
________________________________________
Inheritance Tax Planning
For many families, trusts form part of wider inheritance tax planning rather than being used solely to protect young beneficiaries.
Inheritance Tax (IHT) is primarily governed by the Inheritance Tax Act 1984.
Whether creating a trust reduces inheritance tax depends upon:
- the type of trust;
- the value of the assets;
- when gifts are made;
- whether exemptions apply;
- the wider value of your estate.
There is no single inheritance tax solution that suits every family. For example:
- some lifetime gifts may become exempt if the donor survives seven years;
- some transfers into trust may create an immediate inheritance tax charge;
- some trusts are subject to ongoing periodic charges;
- different tax rules apply to different categories of trust.
Because of these complexities, inheritance tax planning should never be considered in isolation from your overall estate planning.
According to the private client solicitors at Bonallack & Bishop, the best inheritance tax planning usually balances tax efficiency with practical family objectives rather than focusing solely on reducing tax.
________________________________________
Can A Trust Protect Family Wealth?
A trust cannot guarantee that assets will always be protected. However, it can often provide significantly greater protection than making an outright gift.
Depending upon its terms, a trust may help protect assets from:
- financial immaturity;
- excessive spending;
- undue influence;
- relationship breakdowns;
- creditor claims in some circumstances;
- future family disputes.
Every situation is different. Whether protection is achieved depends upon the trust structure, the surrounding circumstances and future legal developments.
________________________________________
Can Grandchildren Receive Income From A Trust?
Yes, some trusts allow beneficiaries to receive income while preserving the capital.
Others allow trustees to decide:
- whether income should be distributed;
- when payments should be made;
- which beneficiaries should benefit.
This flexibility can be particularly useful where grandchildren have different financial needs at different stages of life.
________________________________________
Who Should Act As Trustees?
Choosing the right trustees is one of the most important decisions you will make. It’s very important that your trustees should be:
- trustworthy;
- financially responsible;
- organised;
- willing to act over many years;
- capable of making balanced decisions
Many people appoint between two and four trustees. Common choices include:
- parents;
- adult children;
- siblings;
- close family friends;
- professional trustees;
- solicitors.
Some families choose a combination of family members and a professional trustee to provide both personal knowledge and legal expertise.
________________________________________
Can A Trust Fund for Grandchildren Be Changed Later?
That depends on your particular circumstances. Some trusts are intentionally flexible. Others, however, are designed to be permanent. Whether changes are possible depends upon:
- the wording of the trust deed;
- the powers given to trustees;
- the agreement of beneficiaries in some circumstances;
- the relevant law.
For this reason, it is important to think carefully about future family circumstances before the trust is established.
________________________________________
Do Trusts Need Ongoing Administration?
Yes, they do because creating a trust is only the beginning. Trustees may have ongoing responsibilities including:
- maintaining records;
- preparing trust accounts;
- making investment decisions;
- complying with tax reporting obligations;
- considering distributions;
- keeping appropriate documentation.
Depending upon the trust, there may also be registration requirements through HMRC’s Trust Registration Service (TRS).
Professional advice can help trustees comply with these obligations and reduce the risk of mistakes.
________________________________________
Why Specialist Legal Advice Matters
Trust law is one of the most technically complex areas of private client practice. A trust that appears straightforward can have significant legal and tax consequences many years after it has been created.
In particular, choosing the wrong type of trust can:
- produce unexpected tax liabilities;
- restrict future flexibility;
- create disputes between beneficiaries;
- fail to achieve the family’s objectives.
According to the trust solicitors at Bonallack & Bishop, taking specialist advice before establishing a trust is usually considerably less expensive than correcting mistakes after the legal vehicle has been created.
________________________________________
Trust Funds for Grandchildren – Why Choose Bonallack & Bishop?
Every family is different. We take time to understand your objectives before recommending the most appropriate trust structure.
Our solicitors regularly advise clients on:
- trust funds for grandchildren;
- inheritance tax planning;
- lifetime gifting;
- family wealth protection;
- trusts for vulnerable beneficiaries;
- trust administration;
- trustee responsibilities;
- estate planning.
Whether you wish to place a modest investment into trust or establish a long-term family wealth planning strategy, we can explain your options in clear, practical English.
Contact Our Trust Solicitors
If you are thinking about setting up a trust fund for your grandchildren, our experienced private client team would be pleased to help.
We can advise you on:
- the most suitable type of trust;
- inheritance tax implications;
- protecting family wealth;
- trustee appointments;
- drafting the trust;
- ongoing trust administration.
Contact Bonallack & Bishop today to arrange an initial discussion with one of our trust solicitors.
________________________________________
Trust Funds for Grandchildren – Frequently Asked Questions
What are the best trust funds for grandchildren in the UK?
There is no single best type of trust. The most suitable option depends on your objectives, the value of the assets, the ages of your grandchildren and any inheritance tax considerations. Common options include Bare Trusts and Discretionary Trusts.
Can grandparents set up a trust funds for grandchildren?
Yes. Grandparents can establish trusts during their lifetime or through their Will. The most appropriate structure depends on their family circumstances and estate planning objectives.
Is a Bare Trust or a Discretionary Trust better for grandchildren?
Neither is automatically better. A Bare Trust gives the beneficiary an absolute entitlement, usually at age 18, whereas a Discretionary Trust allows trustees greater flexibility over when and how assets are distributed.
Can a trust pay school fees?
Yes. Depending on the terms of the trust, trustees may use trust funds to pay school fees and other educational expenses for beneficiaries.
Can a trust pay university costs?
Yes. Trustees may pay tuition fees, accommodation costs and other educational expenses where permitted by the trust deed.
Does putting money into trust avoid inheritance tax?
Not necessarily. Different inheritance tax rules apply to different types of trusts. Some transfers into trust may have immediate inheritance tax consequences, while others may form part of longer-term inheritance tax planning.
At what age do grandchildren receive money from a trust?
That depends on the type of trust. In a Bare Trust, beneficiaries usually become entitled to the trust assets at age 18 in England and Wales. Other trusts may allow distributions at different ages or give trustees discretion over timing.
Do I need a solicitor to set up a trust?
Although it is possible to create some trusts without legal advice, trusts can have significant legal and tax consequences. Taking specialist legal advice helps ensure that the trust is properly drafted and achieves your objectives.


